Private Health Cover, Built for Busy Tradespeople
Get treated faster. Get back to work sooner. Get AdviceHealth cover that keeps you earning.
When your work depends on your body, waiting months for treatment isn’t just inconvenient, it can stop your income overnight.
Whether you’re a builder, plumber, electrician, carpenter or contractor, private medical insurance can help you get diagnosed and treated sooner, so you can get back to work and keep your business moving.
At Insure My Health, we make the whole thing simple. Absolute clarity from a broker who understands how important your health is to your livelihood.
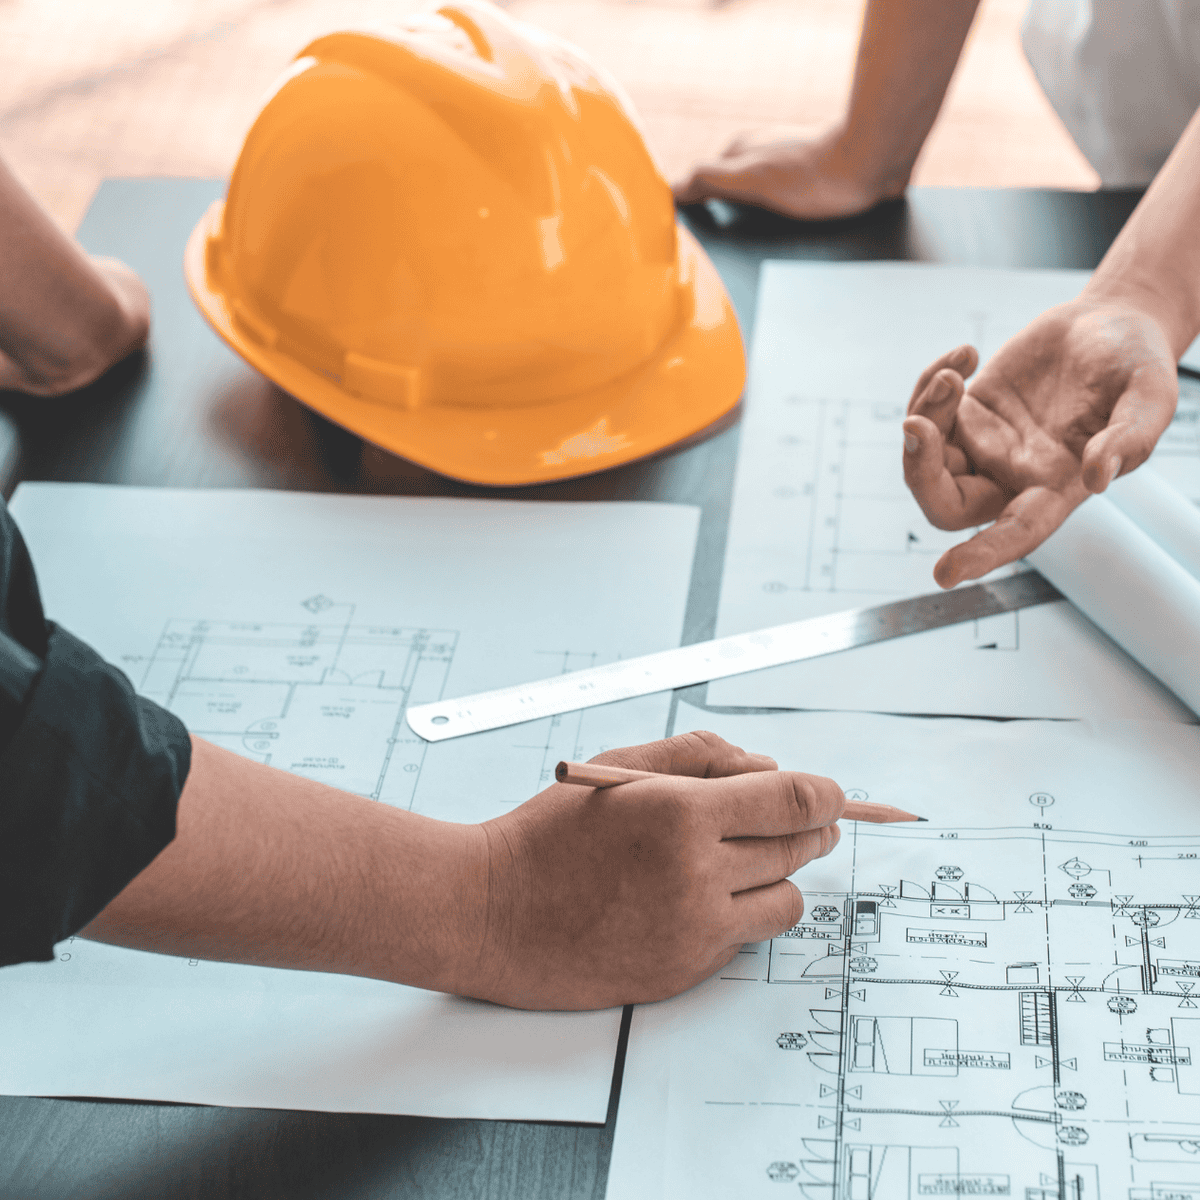
If you’re self‑employed, there’s no sick pay, no HR department and no colleague who can step in when you’re injured. A shoulder, knee or back problem can stop your work instantly, and every day off the tools has a cost.
Private medical insurance doesn’t replace income (that’s what income protection is for), but it can help you:
Faster diagnosis and treatment
No waiting months to find out what’s wrong and even longer waiting to be treated.
Less time off the tools
Helping you get back to work sooner, continuing to earn.
Skip long NHS waiting lists
Keep your projects moving by not adding to the 7.8million currently on waiting lists.
Stay on track with business commitments
Not having to delay important jobs or letting your clients down.
Protect client relationships
By reducing downtime and keeping your reputation strong.
The Financial Impact of Being Off Work
Without private medical insurance, delays in diagnosis or treatment can mean time away from work—and income left unbilled.
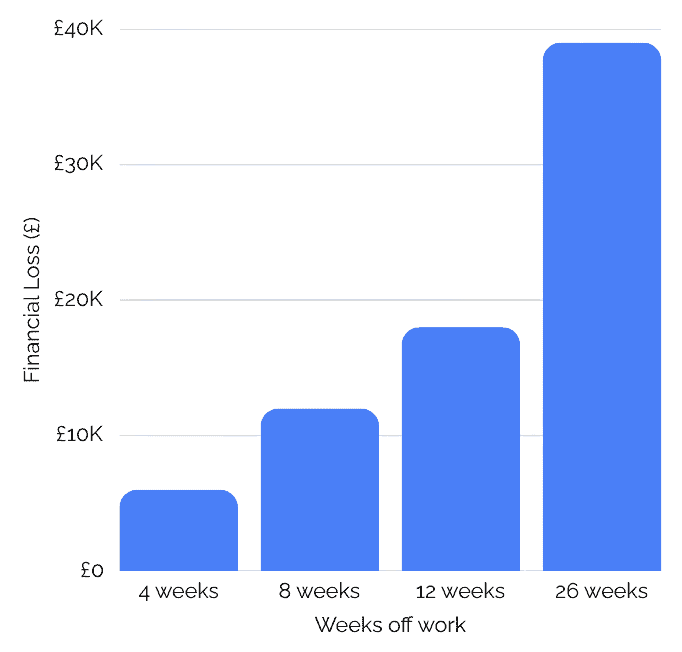
The cost of time away
At £300 per billable day, estimated gross billings add up quickly:
More than a missed invoice
A long absence can also affect cash flow, client commitments and the time it takes to get your business back on track. Actual financial impact depends on your work, savings, support and ability to catch up later.
Reduce disruption where you can
Faster access to eligible diagnosis and treatment may help limit time away from work. Cover, exclusions, underwriting and access to providers vary by policy.
Lost billable income is only one part of the potential financial impact. A prolonged period away from your trade can affect the business you’ve spent years building.
What Health Insurance Can Cover
Remote GP Access
Speak to a GP by phone or video without losing half a day travelling to a surgery.
Outpatient Diagnostics
Consultations, blood tests, X‑rays, ultrasounds, MRI and CT scans.
This is often the most important part as you can’t fix a problem until you know what’s causing it.
Hospital Treatment
Eligible surgery, consultant fees, anaesthetist fees and hospital care.
Therapies
Physiotherapy, osteopathy, chiropractic treatment – essential if your job is physically demanding
Cancer Cover
Comprehensive cancer benefits vary by insurer, but most include diagnosis, treatment and ongoing support.
Outpatient Cover - The Hidden Gem
Most people think private health insurance is all about big operations and overnight stays. The truth is, the real value often sits quietly in the background – outpatient cover.
This is the part of your policy that helps you get answers quickly. Scans, tests, specialist consultations, all the things that move you from worry to clarity without waiting months.
Why it matters
Fast diagnosis
Outpatient cover gets you in front of the right specialist quickly, so you’re not stuck in the NHS waiting cycle.
Early reassurance
Most health concerns are solved at the diagnostic stage. Outpatient cover is what gets you there.
Avoid delays
Without it, you may still have private treatment… but only after the NHS has diagnosed you. That’s where people get caught out.
The bit most people miss
Outpatient cover is often the difference between:
- weeks of uncertainty
- or a clear plan within days
It’s the quiet workhorse of private medical insurance, not flashy, not complicated, just incredibly useful when you need answers fast.
If you want a policy that genuinely feels private, not just private treatment bolted onto NHS waiting times, outpatient cover is the hidden gem worth keeping.
We’ll walk you through the options in plain English and help you choose a level that fits your budget without losing the benefits that matter.
Frequently Asked, but very important Questions.
Can I get health cover if I'm self employed?
Yes. Self-employed tradespeople can take out private medical insurance in the same way as other individuals, subject to the insurer’s eligibility, underwriting, terms and conditions.
Is Private Health Insurance Worth It for a Self-Employed Tradesman?
That comes down to your personal buffer. If you had to stop working for three or six months, could you comfortably cover your household bills, van finance, and business overheads? Private health insurance does not replace lost income, but it helps you dodge long NHS waits so you can get diagnosed and treated faster. For many tradespeople, getting back on the tools a few weeks sooner pays for the policy many times over.
Cancer Cover, Optional Benefits, and Pre-Existing Medical Conditions
This covers a few important areas:
-
Cancer Cover: Comprehensive cancer care is a cornerstone of private medical insurance, though exact treatment and drug benefits vary between providers.
-
Optional Benefits: Extras like dental or optical cashback can be added, but it is always best to nail down your core medical cover first.
-
Pre-Existing Medical Conditions: Policies usually focus on new illnesses arising after your start date. Depending on whether you choose moratorium or full medical underwriting, past issues might be excluded until you have been clear of symptoms for a set period.
Can I Get Private Health Insurance If I Already Have an Injury?
Yes, you can still take out a policy. However, the insurer will likely exclude your current injury from coverage because it counts as a pre-existing condition. Even so, the policy remains valuable protection against any completely new health issues or injuries that crop up down the line.
Sole Trader or Limited Company: Does It Matter?
Yes, because your business structure changes how your cover works. Sole traders usually buy personal policies out of their own pocket. If you run a limited company, you can often arrange business health insurance through the company. Keep in mind that employer-paid policies count as a taxable benefit in kind, so it is always wise to chat with your accountant first.
Hospital Choice: Does It Matter?
It makes a big difference to both your care and your monthly cost. Most policies offer nationwide networks covering major groups like Spire and Nuffield. You can choose full hospital access or a guided option. Guided options lower your monthly bill, but you give up the freedom to pick a specific consultant or hospital if you have someone particular in mind.
What About Physiotherapy and Other Therapies?
When your job relies on physical strength and mobility, therapies are vital. Good policies cover physiotherapy, osteopathy, and chiropractic treatment. Some insurers bundle these into a general outpatient pot, while others offer a dedicated therapy allowance. Checking how these are structured helps you avoid nasty surprises when your joints start aching.
How Much Does It Cost?
(A better question is: What level of cover can I get for the budget I’m comfortable spending?)
There is no single meaningful price. The premium can depend on factors including:
ⓘ Your trade
ⓘ Your age
ⓘ Where you live
ⓘ How much outpatient cover you want
ⓘ Hospital Access
ⓘ Your chosen exces
Why Choose Insure My Health?
Clear, honest guidance
Straightforward explanations without jargon or sales pressure.
All market comparison
We check the UK’s leading insurers and show you the differences clearly.
Personal support
You will always speak to a human, not a call centre, whenever you need help.
Help beyond the setup
Claims, renewals, questions, we stay with you long after the policy starts.
Built for tradespeople
Advice shaped around the realities of working on the tools and protecting your income.
Simple from start to finish
A quick chat – clear options – and everything arranged for you.

